Medicare Open Enrollment 2027: Read One Letter Before Dec 7
Medicare Open Enrollment is open right now. It closes December 7.
Most people can do nothing at all. That’s fine.
But only after you read one letter. Most people toss it in a drawer.
Here’s that letter, the three things to look for, what drugs cost in 2027, and the one switch that can cost you for years.
Medicare Open Enrollment runs October 15 to December 7, 2026, and changes start January 1, 2027. You can switch between Original Medicare and Medicare Advantage, change Advantage plans, or join, switch or drop a drug plan. If your plan's Annual Notice of Change shows no problems, you can do nothing.
Lisa and I both collect Social Security. And I’m on Medicare myself: Part B, a Part D drug plan and Medigap Plan G.
So every fall, I get the same letter you do.
And every fall, I see the same thing. People think Open Enrollment means they have to shop. They don’t.
Most people can sit tight. The trick is knowing if you’re one of them.
That takes about ten minutes and one letter. Let me show you.
One thing first. I don’t sell insurance, and no plan pays me. This is a plain guide built on Medicare’s own papers, not insurance advice.
When Is Medicare Open Enrollment for 2027?
Medicare Open Enrollment runs from October 15 to December 7, 2026. Any change you make starts January 1, 2027. Miss December 7, and most people keep the plan they have for 2027. People in a Medicare Advantage plan get one more chance, from January 1 to March 31.
Here’s the whole season on one line:
Five dates. Only one of them is a deadline.
December 7. Circle it.
That January to March window is narrow. It’s only for people already in a Medicare Advantage plan. And you get one change. Just one.
So if you plan to change, do it now. Not in February.
What Can You Change Before December 7?
During Open Enrollment you can switch from Original Medicare to a Medicare Advantage plan, or back. You can change to a different Advantage plan. And you can join, switch or drop a Part D drug plan. Medicare.gov puts the start date plainly: “The changes you make during Open Enrollment are effective January 1 of next year.”
Quick word check, so the rest makes sense:
- Original Medicare is the government plan. Part A covers the hospital. Part B covers doctors.
- Medicare Advantage is a private plan that replaces Original Medicare. It’s also called Part C. Most have a network of doctors.
- Part D is a drug plan.
- Medigap is extra insurance that helps pay what Original Medicare doesn’t. It’s also called a Medicare Supplement.
Here’s what each change does:
| If you have | You can switch to | Starts |
|---|---|---|
| Original Medicare | A Medicare Advantage plan | January 1 |
| A Medicare Advantage plan | Original Medicare, plus a drug plan | January 1 |
| A Medicare Advantage plan | A different Advantage plan | January 1 |
| A Part D drug plan | A different drug plan, or none | January 1 |
One warning about dropping a drug plan.
If you go without drug coverage and have nothing else that counts, Medicare can charge you a late penalty. It gets added to your premium for as long as you have a drug plan.
Don’t drop it just to save a few dollars.
Do You Have to Do Anything During Open Enrollment?
No. If you do nothing, your plan usually keeps going on January 1. But “usually” is the catch. Plans change their prices, their drug lists and their doctors every year. Your plan has to tell you what’s changing, in a letter called the Annual Notice of Change.
Medicare’s own handbook, Medicare & You 2027, says the letter “includes any changes in coverage, costs, provider networks, service area, and more that will be effective in January.”
It also says when it comes. Your plan sends it by September 30. It may come in the mail. It may come by email.
Can’t find it? The handbook says it straight: “If you don’t get these important documents in early fall, contact your plan.” Call your plan. The phone number is on your member card. Ask them to send it again.
Or log in at Medicare.gov. The page called Your Plan Summary shows the plan you have now, its premium and your Medigap company. That’s where I checked mine.
Here’s my own fall, so far.
My drug plan is Wellcare Value Script. In 2026 it costs me $2.70 a month. My Medigap Plan G is with Physicians Mutual.
Open Enrollment doesn’t touch my Medigap plan. My drug plan is the one that can change. Its letter came a couple of weeks ago.
Here’s what changes. I looked my plan up in Medicare’s plan finder for 2027:
| My Wellcare Value Script | 2026 | 2027 |
|---|---|---|
| Monthly premium | $2.70 | $5.30 |
| Drug deductible | $615 | $700 |
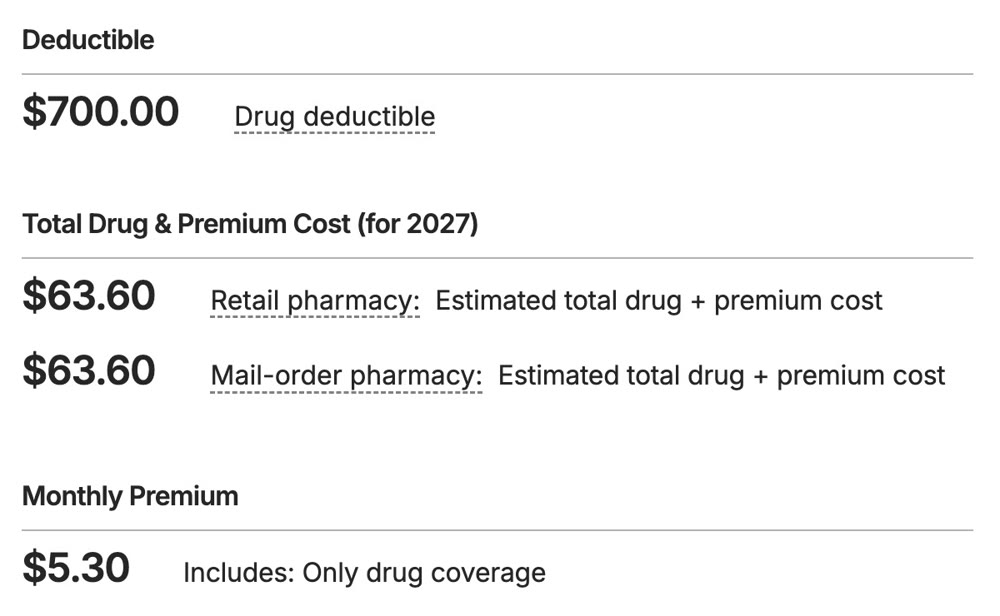
The premium almost doubles.
Sounds scary. Do the math, though. It’s $2.60 more a month, or $31.20 for the year.
And the bigger deductible? It doesn’t touch me. My drug is a cheap generic on Tier 1, and my plan’s deductible only applies to Tiers 2 to 5. The plan finder puts my whole 2027 bill, drug plus premium, at $63.60 for the year.
If your drug sits on Tiers 2 to 5, it’s a different story. You pay the first $700 yourself.
Same plan. Same letter. Very different bill, depending on one line.
That’s exactly the kind of change the letter is there to show you.
Then a second letter showed up. This one was from Physicians Mutual. My Medigap rate is going up too.
More on that one in a minute. It’s a different animal.
If you have an Advantage plan, yours covers everything at once. Doctors, hospital and usually drugs. Read the whole thing.
Three Things to Check in Your Annual Notice of Change
You only need three answers from that letter. Are my drugs still covered? Are my doctors still in the plan? What will I pay next year? If all three look fine, you’re done. Put the letter away. If one doesn’t, it’s time to compare plans.
Here’s where to look, and what should make you stop:
| Check | Where to look in the letter | Stop and compare if… |
|---|---|---|
| My drugs | The part about the drug list, sometimes called the formulary | A drug you take is dropped, or moves to a higher tier |
| My doctors | The part about the network, if you have an Advantage plan | Your doctor or hospital is leaving the plan |
| My cost | Premium, deductible and copays for 2027 | Any of them goes up more than you can live with |
Get a pen. Circle anything that changed. Then ask yourself one question: can I live with this for all of 2027?
Here’s the whole decision:
How Do You Compare Medicare Plans for 2027?
Use Medicare’s free plan finder at medicare.gov/plan-compare. Type in your ZIP code, your drugs and your pharmacy. It lists the plans in your area and what each would cost you for the year. Rather talk to a person? Call 1-800-MEDICARE, or get free one-on-one help from your local SHIP office.
Here’s the order I’d follow:
- Go to medicare.gov/plan-compare. You don’t need an account to look.
- Pick the year. Make sure it says 2027, not 2026.
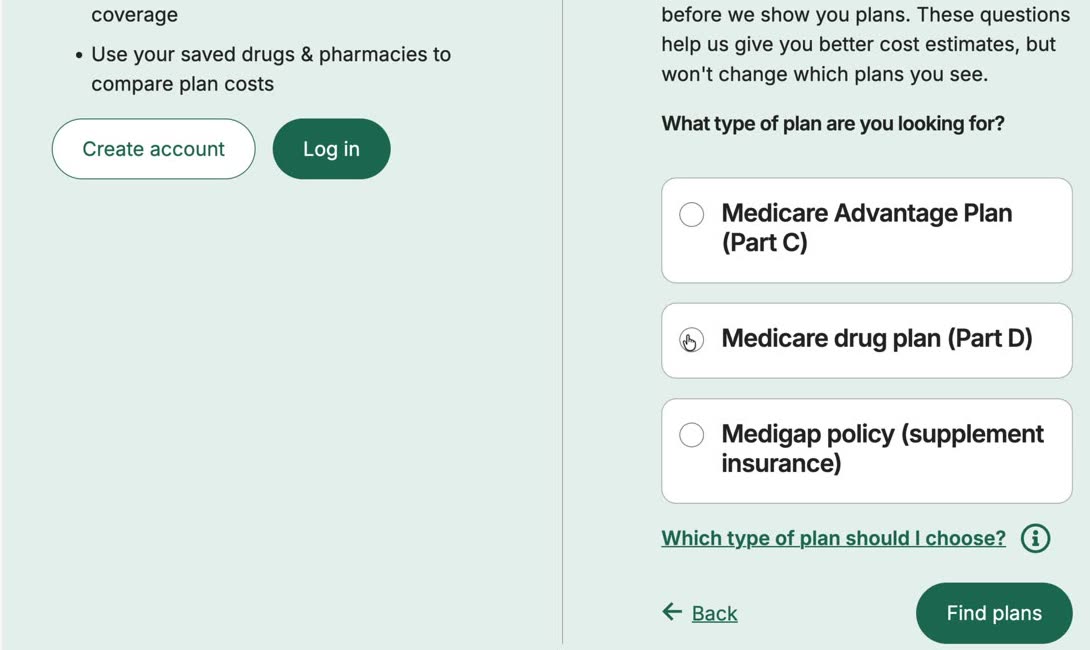
- Pick the type of plan you’re shopping for.
- Say yes when it asks about drug costs. Then add every drug you take, with the dose.
- Add the pharmacy you use. Prices change from one pharmacy to the next.
- Sort the results by total yearly cost, not just the premium.
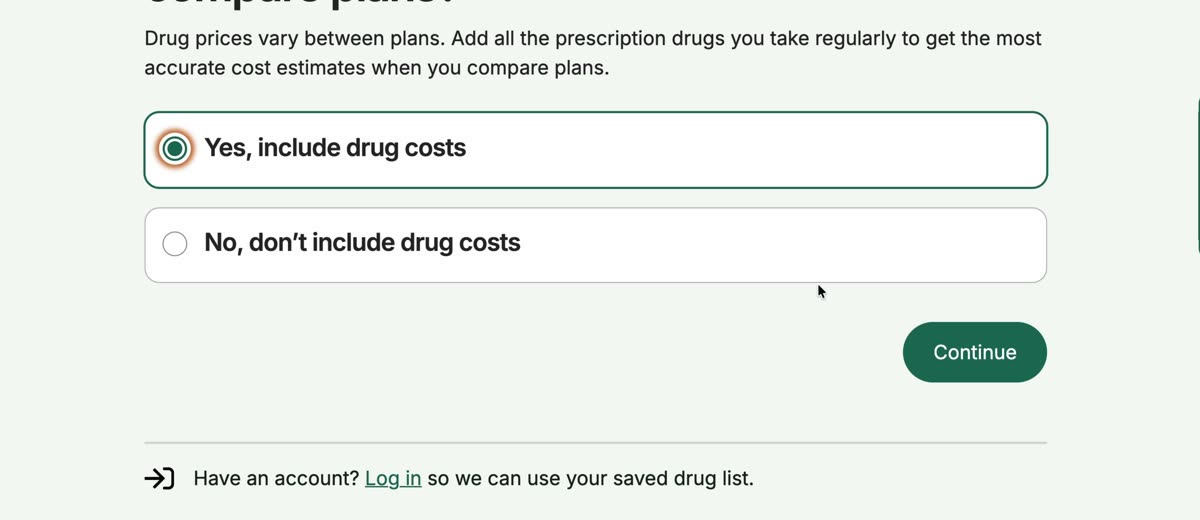
Why total cost? Because a $0 premium plan can still cost more by December. The premium is just the cover charge.
Would you rather talk to a real person?
- 1-800-MEDICARE (1-800-633-4227). TTY users can call 1-877-486-2048.
- SHIP, your State Health Insurance Assistance Program. It’s free, one-on-one help, and they don’t sell anything. Find yours at shiphelp.org.
SHIP is the best-kept secret in Medicare. A real counselor, in your state, on your side.
What Will Medicare Drugs Cost in 2027?
The yearly cap on what you pay for covered drugs rises from $2,100 in 2026 to $2,400 in 2027. The most a drug plan can charge as a deductible rises from $615 to $700. Both figures come from the 2027 Rate Announcement from CMS, the agency that runs Medicare.
Here’s the good news in that cap.
Medicare & You 2027 says that once you reach it, “you’ll pay $0 for your covered Part D drugs for the rest of the year.”
$2,400 is the most. Not the bill.
Most people pay far less. But if you take an expensive drug, that cap is a floor under your feet. You can plan around it.
Three more 2027 changes worth knowing:
- Lower prices on 15 more drugs. Medicare negotiated prices for 15 drugs, starting January 1, 2027. They include Ozempic, Rybelsus and Wegovy, Trelegy Ellipta, Breo Ellipta, Xtandi, Ibrance, Linzess, Tradjenta, Janumet and Otezla. CMS estimates people will save $685 million out of pocket. What you pay still depends on your plan, so check the price in the plan finder.
- Some weight-loss drugs. The handbook says Medicare “now also offers access to certain GLP-1 drugs to help you lose weight if you meet certain requirements.” Ask your doctor if you qualify.
- Extra Help. If your income is limited, Extra Help can cut your drug costs a lot. In 2027 you’d generally pay no more than $5.80 for a generic and $14.40 for a brand-name drug, per the handbook. Ask 1-800-MEDICARE if you qualify.
What is the Medicare Prescription Payment Plan?
It’s a free way to spread your drug costs into monthly bills, instead of paying a lot in January. It helps if you hit big drug bills early in the year.
But Medicare.gov is blunt about what it does not do: “It doesn’t save you money or lower your drug costs.”
It spreads the bill. It doesn't shrink it.
If you’re already in it and stay in the same plan, it renews for 2027. If you switch drug plans, you sign up again with the new plan.
Can You Switch From Medicare Advantage Back to Medigap?
You can always leave an Advantage plan for Original Medicare during Open Enrollment. Getting a Medigap policy to go with it is the hard part. Outside a few special windows, a Medigap company can ask about your health, charge you more, or say no. So call the Medigap company and get approved before you switch.
This is the trap I promised you.
Here’s how it springs. Say you joined an Advantage plan a few years ago. Now your doctor left the network. You want Original Medicare back, plus a Medigap plan like mine.
Medicare lets you go back. No problem.
But Medigap isn’t Medicare. It’s sold by private insurance companies. And Medicare’s own Medigap guide, Choosing a Medigap Policy, says this about buying one outside your first window: “They may deny you a policy unless you have a guaranteed issue right.”
That first window is your Medigap Open Enrollment Period. It’s six months, and it starts when you’re 65 or older and have Part B. The guide says it “doesn’t repeat every year.”
Six months, once. That’s it.
Think of it like a one-way gate on a ranch road. Easy to drive through. Not always open when you want to come back.
The exception: your trial right
You may get a do-over if you’re in your first year with an Advantage plan. The Medigap guide calls it a trial right. It covers two cases:
- You joined an Advantage plan when you first got Medicare at 65, and you want out within the first year.
- You dropped a Medigap policy to join an Advantage plan for the first time, and you’ve been in it less than a year.
In those cases, a Medigap company generally can’t turn you down.
A few states also give you extra rights to buy or switch Medigap. Your SHIP counselor knows your state’s rules.
The safe order
- Call one or two Medigap companies first. Ask: “Will you sell me a policy, and at what price?”
- Get the yes in writing, and ask them to start your policy on January 1.
- Then switch to Original Medicare and pick a Part D drug plan, all by December 7.
What If Your Medigap Rate Goes Up?
A Medigap rate increase has nothing to do with Open Enrollment. Medigap isn’t on the Open Enrollment list at all. You can apply to a different Medigap company any month of the year. The catch is the same one as before: outside your first window, the new company can check your health and say no.
That’s the note I got from Physicians Mutual.
So why do Medigap rates go up? Medicare’s Medigap guide says each company prices its policies one of three ways:
| How the company prices it | What that means for you |
|---|---|
| Community-rated | Everyone pays about the same, whatever their age |
| Issue-age-rated | Your price is based on how old you were when you bought it |
| Attained-age-rated | Your price goes up as you get older |
All three can still rise. The guide says premiums “may go up because of inflation and other factors.”
Here’s the part that matters when you shop. The same guide says: “Price is the only difference between policies with the same letter sold by different companies.”
Think about that.
A Plan G is a Plan G. Same benefits, whoever sells it.
So when your rate goes up, a quote from another company is worth a phone call.
What to do with a Medigap rate notice:
- Ask your company which of the three ways your policy is priced. The guide suggests asking how often the premium goes up because of your age.
- Get quotes for the same plan letter from two or three other companies. SHIP can help you compare.
- If you’re healthy, ask the new company if they’ll take you. Get the yes in writing.
- Don’t cancel your old policy until the new one starts.
If your health makes a switch risky, staying put may be the smart move, even at a higher price. A higher bill beats no Medigap at all.
Who Is Really Calling You “From Medicare”?
Probably not Medicare. Medicare.gov says it plainly: “Medicare will never call you to sell you anything or visit you at your home.” If someone calls about a “new Medicare card” or a better plan, hang up. Never give your Medicare number to a caller.
Open Enrollment is scam season.
The phone rings. A friendly voice says, “I’m calling from Medicare about your new card.” Or “You qualify for more benefits.”
Hang up.
Medicare.gov’s fraud page lists what Medicare won’t do. One of them: it won’t “join a Medicare health or drug plan over the phone, unless you called and asked for help.”
Your Medicare number is like a key to your house. Give it to your doctor, your plan and your SHIP counselor. Nobody else.
Got a call like that? Report it to 1-800-MEDICARE.
Not sure if an email or text is real? I showed how to ask ChatGPT “Is this a scam?” in plain words. It takes about ten seconds.
What My Guide Can’t Tell You
Here’s where I have to stop, and where my guide could fall short for you:
- Your plan’s numbers. Only your Annual Notice of Change and the plan finder know them. I can’t see them.
- The 2027 Part B premium. Medicare hadn’t announced it on October 28, 2026. It usually comes out in the fall. My COLA guide shows how it eats into the 2027 raise.
- Your state’s Medigap rules. A few states give extra rights. SHIP knows yours.
- Which plan is best for you. I won’t tell you, and I’m not licensed to. That’s what SHIP and the plan finder are for.
- The negotiated drug prices. They’re what Medicare pays drug makers. Your copay depends on your plan.
Who Should Shop This Fall, and Who Can Sit Tight
You can likely sit tight if:
- Your letter shows the same drugs, the same doctors and a cost you can live with.
- You’re on Original Medicare with Medigap, and your drug plan’s letter looks fine. That’s my drug plan this year.
Take a closer look if:
- A drug you take was dropped, or its price jumped.
- Your doctor or hospital left your Advantage plan’s network.
- You moved, or your health changed a lot this year.
- Your Medigap company sent a rate increase. Get quotes for the same plan letter.
- Your income is limited. You may qualify for Extra Help with drug costs.
And if your income is higher, your Part B premium may cost more. My IRMAA calculator shows where you stand.
Your Open Enrollment Plan, Step by Step
You’ve handled harder things than a letter from an insurance company. Raising kids. Paying off a house. Medicare’s paperwork looks big. It’s just a few questions in the right order.
Here they are.
- This weekend: find your Annual Notice of Change. Daylight saving time ends Sunday, November 1. Change the clocks, then read the letter. Same day, every year.
- Can’t find it? Phone your plan, using the number on your member card, and ask for a new copy. Or log in at Medicare.gov and open Your Plan Summary.
- Check three things: your drugs, your doctors, your 2027 cost. All fine? Stop there.
- Something changed? Compare plans at medicare.gov/plan-compare with your drugs and pharmacy, or call SHIP for free help.
- The step most people skip: if you’re leaving Advantage for Medigap, call the Medigap company and get a yes before you switch. Skip this and you could end up with no Medigap at all.
- By December 7: make your change. Your new plan starts January 1. Watch the mail for a welcome letter and a new member card.
- Hang up on anyone who calls “from Medicare.” All season long.
Torn Between Medicare Advantage and Medigap?
Here’s the question I get most this time of year. Which costs less, Advantage or Medigap?
The honest answer is: it depends on how much care you use. A low-premium Advantage plan can look cheap in a healthy year. A rough year can change that fast.
So I built a free tool for it: my Medicare Advantage vs Medigap cost calculator. Put in the quotes you got. It shows a full year of costs, side by side, for the year you expect and for a worst year. It also shows how much care it takes before Medigap becomes the cheaper one. Your numbers never leave your device. No sign-up, no sales call.
It’s the same tool from the end of the video. On TV, I give it the short address: robfore.com/medigap.
All my other free retirement tools are on my calculators page.
Bless and be blessed,
Sources
- Medicare & You 2027 handbook (enrollment periods, Annual Notice of Change, $2,400 drug cap, $700 deductible, Extra Help, plan finder, phone numbers) - checked Oct 28, 2026
- Medicare.gov, Open Enrollment (dates, what you can change, January 1 start) - checked Oct 28, 2026
- CMS, Announcement of Calendar Year 2027 Medicare Advantage Capitation Rates and Part C and Part D Payment Policies, Table V-2 (Part D deductible and out-of-pocket threshold) - checked Oct 28, 2026
- CMS, Medicare Drug Price Negotiation Program: Negotiated Prices for Initial Price Applicability Year 2027 (the 15 drugs, $685 million estimate) - checked Oct 28, 2026
- Wellcare, 2027 Summary of Benefits, Wellcare Value Script (PDP) and Wellcare Classic (PDP), Nevada row ($5.30 premium, $700 deductible on tiers 2-5) - checked Oct 28, 2026
- Medicare.gov, Medicare Prescription Payment Plan - checked Oct 28, 2026
- Optum, 3 key changes in 2027 for patients with Medicare Part D (payment plan renewal and re-enrolling after a plan change) - checked Oct 28, 2026
- Medicare.gov, Choosing a Medigap Policy (Medigap Open Enrollment Period, medical underwriting, trial rights) - checked Oct 28, 2026
- Medicare.gov, Reporting Medicare fraud and abuse - checked Oct 28, 2026
- SHIP, State Health Insurance Assistance Programs (free local counseling) - checked Oct 28, 2026